
Leading Companies in the Global Copper Tubes Market
Author:
Intellectual Market Insights Research
Published Date:
29 Aug 2026
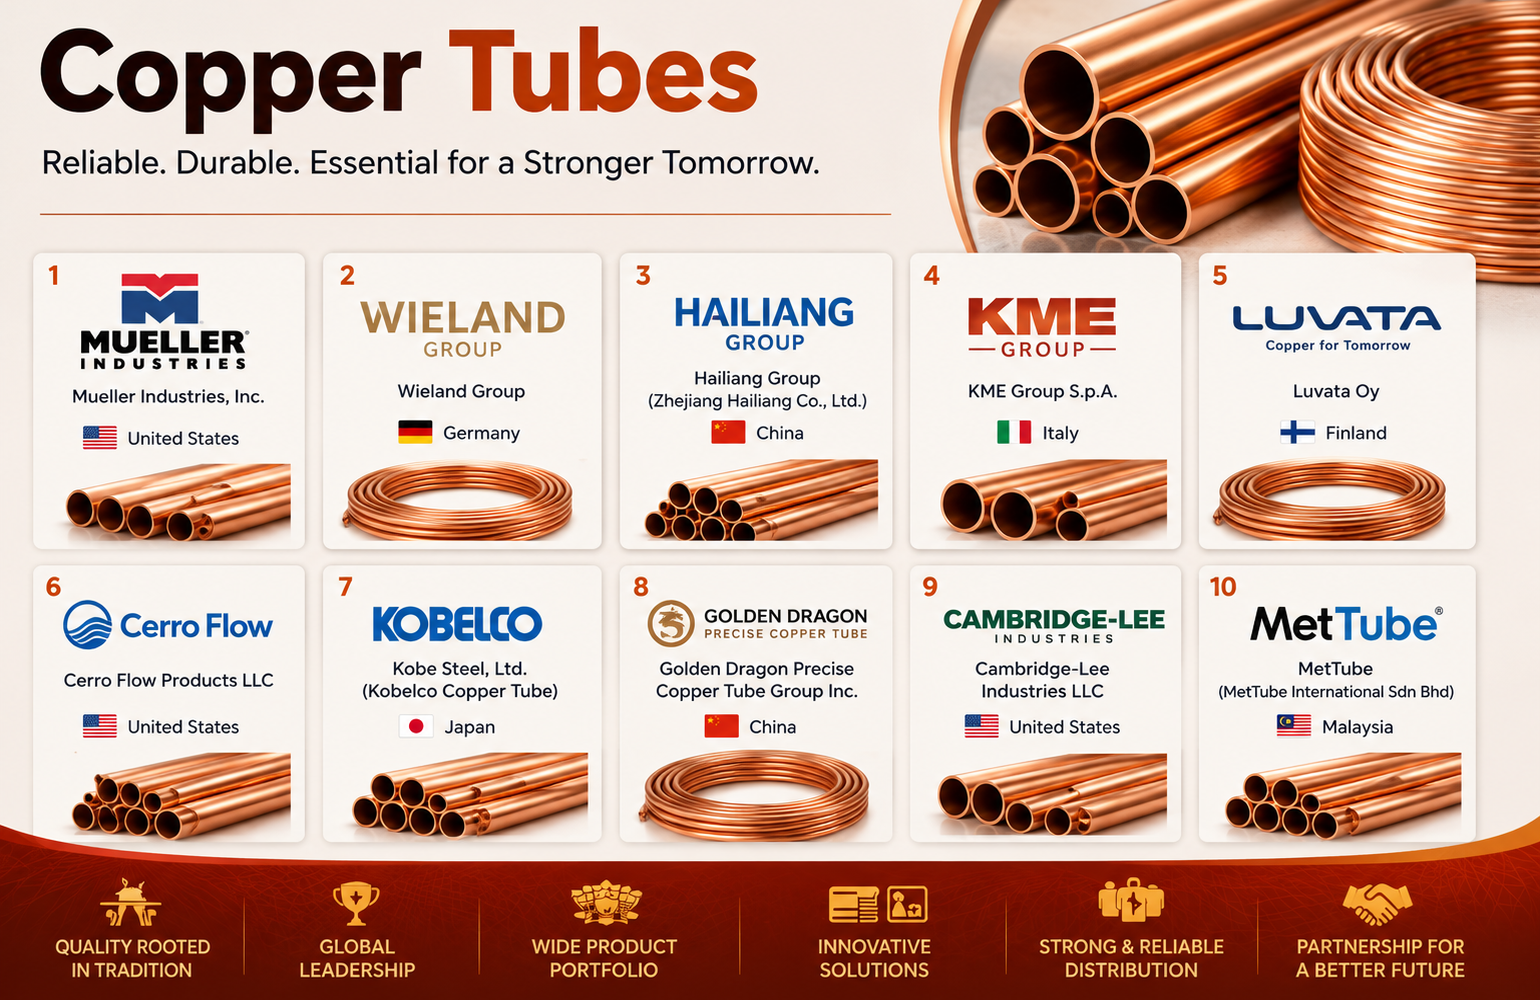
Top 10 Key Players in the Copper Tubes Market: Industry Leaders Shaping the Future
Copper tubes remain one of the most trusted materials in modern piping and heat-transfer systems, prized for their corrosion resistance, thermal conductivity, non-combustibility, and long service life. From water distribution and drainage lines to air-conditioning coils and industrial heat exchangers, copper tubing sits at the intersection of construction, HVAC/R, and the broader energy transition, with newer growth coming from heat pumps, electrification, and renewable-energy infrastructure.
The global copper tubes market was valued at approximately USD 46.22 billion in 2025 and is projected to reach USD 80.29 billion by 2034, expanding at a compound annual growth rate (CAGR) of 6.4% over the forecast period. This growth reflects rising construction and renovation activity, the accelerating global rollout of heat pumps and energy-efficient HVAC systems, and copper's continued dominance in applications where reliability and thermal performance cannot be compromised.
The competitive landscape is anchored by large, vertically integrated copper and copper-alloy processors, Mueller Industries, Wieland Group, KME Group, and Kobe Steel, whose tube businesses sit alongside broader rod, strip, and fitting portfolios. Alongside these established names, Hailiang Group has emerged as the volume leader out of China through an aggressive string of acquisitions, while regional specialists such as Cerro Flow Products, Luvata, Golden Dragon, Cambridge-Lee Industries, and MetTube compete on cost, application specialization, and proximity to end markets.
Understanding which companies lead this large and consolidating market is essential for HVAC/R OEMs, plumbing wholesalers, and industry analysts. This article provides a research-based analysis of the top companies in the global copper tubes market, their positioning, flagship offerings, and the regional and technological forces shaping the competitive landscape.
Market Overview
|
Parameter |
Details |
|---|---|
|
Market Size (2025) |
USD 46.22 Billion |
|
Projected Market Size (2034) |
USD 80.29 Billion |
|
CAGR (2025–2034) |
6.4% |
|
Base Year |
2023 |
|
Forecast Period |
2025–2034 |
|
Leading Region |
Asia-Pacific (led by China's copper tube manufacturing base) |
|
Fastest-Growing Region |
Asia-Pacific, on the back of rising heat pump production and construction activity |
|
Key Growth Drivers |
Heat pump and HVAC/R adoption, construction and plumbing renewal, electrification and renewable-energy demand |
|
Key Challenges |
Copper price volatility, substitution by PEX/aluminum in some plumbing and HVAC applications |
|
Key Opportunities |
Inner-grooved high-efficiency tubes for heat pumps, recycled/circular copper tube production, regional capacity expansion |
Why the Copper Tubes Market Is Growing
1. Expanding Heat Pump and HVAC/R Demand
Global electrification of heating and cooling is driving rapid growth in heat pump manufacturing, particularly in China, which accounts for roughly 40% of global heat pump production and about 50% of exports, and copper coils and refrigerant tubing remain the industry-standard choice for heat exchanger performance.
2. Construction Activity and Plumbing System Renewal
Ongoing residential and commercial construction, along with the replacement of aging or lead-containing plumbing infrastructure, continues to support demand for copper tube in water distribution, heating, and drainage systems.
3. Electrification and Renewable Energy Infrastructure
Growing investment in electric mobility, solar installations, and grid infrastructure is expanding copper's addressable applications well beyond traditional plumbing and HVAC, reinforcing overall demand for copper products including tube.
4. Superior Thermal and Antimicrobial Properties
Copper's high thermal conductivity, corrosion resistance, and natural antimicrobial properties continue to support its preference over plastic or aluminum alternatives in applications where performance and longevity matter most, such as refrigeration coils and medical gas piping.
5. Industrial Heat Exchanger and Process Industry Demand
Power generation, chemical processing, and industrial refrigeration continue to rely on copper tube for heat exchangers, sustaining a steady base of industrial demand alongside the larger HVAC and plumbing segments.
6. Consolidation and Capacity Expansion Among Major Producers
Large processors are actively acquiring capacity and entering new regions, for example Hailiang Group's purchase of tube assets from Luvata and KME, and new joint-venture plants in the Middle East, concentrating scale and reshaping the competitive map.
Top 10 Companies in the Copper Tubes Market
- Mueller Industries, Inc.
- Wieland Group
- Hailiang Group (Zhejiang Hailiang Co., Ltd.)
- KME Group S.p.A.
- Luvata Oy
- Cerro Flow Products LLC
- Kobe Steel, Ltd. (Kobelco Copper Tube)
- Golden Dragon Precise Copper Tube Group Inc.
- Cambridge-Lee Industries LLC
- MetTube (MetTube International Sdn Bhd)
1. Mueller Industries, Inc.
|
Category |
Details |
|---|---|
|
Company Name |
Mueller Industries, Inc. |
|
Headquarters |
Collierville, Tennessee, United States |
|
Founded |
1917 |
|
Employees |
Approx. 4,800 (2025) |
|
Revenue (FY2025) |
Net sales of approx. USD 4.18 Billion, up 10.9% year over year; Piping Systems segment (including copper tube) generated approx. USD 2.71 Billion |
|
Company Overview |
Mueller is the only vertically integrated manufacturer of copper tube and fittings in North America, organized into Piping Systems, Industrial Metals, and Climate segments. |
|
Key Products |
Copper tube in straight lengths and coils, copper and plastic fittings, line sets, valves, and drainage, waste, and vent components under the Mueller Streamline brand. |
|
Market Position |
The leading North American producer of copper tube and fittings, with a dominant position in plumbing and refrigeration tube. |
|
Recent Developments |
Acquired Elkhart Products Corporation, a US copper solder-fittings maker (August 2024), and the Nehring wire and cable business, which lifted Industrial Metals segment sales by 25.1% in 2025. |
|
Strategic Advantages |
Full vertical integration from mining/refining inputs to finished tube, a strong balance sheet, and consistent bolt-on acquisitions that expand product breadth. |
2. Wieland Group
|
Category |
Details |
|---|---|
|
Company Name |
Wieland-Werke AG (Wieland Group) |
|
Headquarters |
Ulm, Germany |
|
Founded |
1820 |
|
Employees |
Approx. 10,279 (FY2024/25) |
|
Revenue (FY2024/25) |
Approx. EUR 6.6 Billion |
|
Company Overview |
Wieland is one of the world's leading suppliers of semi-finished copper and copper-alloy products, expanded in North America through its 2019 merger with Global Brass and Copper Holdings. |
|
Key Products |
Installation and plumbing tube (including tube made from 100% recycled copper), and engineered tube for refrigeration and air-conditioning heat exchangers. |
|
Market Position |
Recognized as a top global leader in copper tube alongside KME Group and Kobe Steel in independent industry quadrant evaluations. |
|
Recent Developments |
Brought a new copper-scrap recycling and billet-casting line into full end-to-end operation, feeding directly into tube production, and completed the Techni-Cast acquisition (December 2025). |
|
Strategic Advantages |
Scale across roughly 89 locations in 40 countries, deep investment in copper recycling and sustainability, and diversification into automotive, e-mobility, and aerospace end markets. |
3. Hailiang Group (Zhejiang Hailiang Co., Ltd.)
|
Category |
Details |
|---|---|
|
Company Name |
Hailiang Group / Zhejiang Hailiang Co., Ltd. |
|
Headquarters |
Zhuji, Zhejiang Province, China (group HQ in Hangzhou) |
|
Founded |
1989, originally as a small copper tube plant |
|
Employees |
10,000+ |
|
Revenue |
Approx. USD 11.7 Billion trailing 12-month (Zhejiang Hailiang, the listed copper-processing arm) |
|
Company Overview |
Hailiang describes itself as the No. 1 producer in the global copper tube and rod processing industry, operating 21 production bases across Asia, the Americas, and Europe. |
|
Key Products |
Copper coil and straight tube, copper busbars, and aluminum tube, with annual copper tube output of roughly 809,000 metric tons. |
|
Market Position |
The largest copper tube producer globally by volume, having grown rapidly through acquisitions of competitors' tube operations. |
|
Recent Developments |
Announced a USD 566 Million joint-venture copper products plant with Saudi Arabia's Rawas (2026) and continued expansion into high-end copper foil. |
|
Strategic Advantages |
Cost leadership at massive scale, an aggressive global M&A track record (including acquiring Luvata's North American tube business and KME's German/Spanish tube and brass rod operations), and backing from a diversified Chinese conglomerate. |
4. KME Group S.p.A.
|
Category |
Details |
|---|---|
|
Company Name |
KME Group S.p.A. (formerly Intek Group) |
|
Headquarters |
Corporate seat in Milan, Italy; principal operating headquarters in Osnabrück, Germany |
|
Founded |
1886 |
|
Employees |
Approx. 5,150 |
|
Revenue |
In the range of approx. EUR 2.0 Billion, reflecting sales of roughly 392,000 tons of copper and copper-alloy products |
|
Company Overview |
KME is one of the world's largest manufacturers of copper and copper-alloy semi-finished products, spanning rolled products, tube, and brass across 12 production sites, mostly in Europe. |
|
Key Products |
Copper tube for building, industrial, and energy applications, alongside its well-known TECU architectural copper products. |
|
Market Position |
Ranked among the top global copper tube producers alongside Wieland and Kobe Steel in the 2025 Copper Tubes Company Evaluation Report. |
|
Recent Developments |
Commissioned a second refining furnace at KME Germany (2025) and secured EUR 300 Million in financing from Apollo Global Management tied to its Cunova buyback. |
|
Strategic Advantages |
Century-plus manufacturing heritage, a concentrated European production footprint, and a diversified portfolio spanning architectural, industrial, and energy-sector copper. |
5. Luvata Oy
|
Category |
Details |
|---|---|
|
Company Name |
Luvata Oy |
|
Headquarters |
Corporate roots in Pori, Finland, with international operations including a UK office in Brentford |
|
Founded |
1910, tracing back to a Finnish copper ore discovery and Outokumpu's early copper operations |
|
Employees |
Several hundred at the core entity, with a broader global workforce across manufacturing sites in six countries |
|
Revenue |
Estimated at approx. USD 5 Billion |
|
Company Overview |
Luvata became part of Japan's Mitsubishi Materials Corporation group in 2017 and supplies copper tube alongside superconductors, ultra-pure copper, and specialty wire products. |
|
Key Products |
Copper tubes, hollow conductors, OFE copper products, and welding products serving automotive, e-mobility, healthcare, and power-generation customers. |
|
Market Position |
A specialist global copper processor recognized as a key player in the copper tubes market, alongside Mueller, Wieland, and Hailiang. |
|
Recent Developments |
Acquired the Dawson Shanahan Group to expand its electroplating and specialty copper capabilities, after earlier divesting parts of its North American tube operations to Hailiang. |
|
Strategic Advantages |
Backing from Mitsubishi Materials, a diversified specialty end-market base beyond conventional plumbing and HVAC tube, and more than a century of Nordic copper-processing heritage. |
Competitive Landscape
The global copper tubes market combines a handful of large, vertically integrated processors with a fast-consolidating volume leader from China and several regionally focused specialists.
Integrated Western and Japanese Processors: Mueller Industries, Wieland Group, KME Group, and Kobe Steel, Ltd. (through its Kobelco Copper Tube business) each run copper tube as part of a broader semi-finished copper and copper-alloy portfolio, giving them scale advantages in raw-material sourcing, recycling, and distribution.
The Hailiang Scale Play: Hailiang Group has become the volume leader globally, leveraging cost-competitive Chinese manufacturing and a string of acquisitions, including tube assets previously owned by Luvata and KME, to build a production base of more than 800,000 metric tons of copper tube annually.
Regional and Application Specialists: Cerro Flow Products (a Marmon Holdings/Berkshire Hathaway company) and Cambridge-Lee Industries compete strongly in the North American plumbing and HVAC/R market, Golden Dragon Precise Copper Tube Group is one of China's largest precision copper tube makers, and MetTube, based in Shah Alam, Malaysia, and backed by South Korea's Poongsan Holdings, serves Southeast Asian and export HVAC/R demand.
Consolidation as the Defining Trend: As the industry matures, competitive differentiation is increasingly shaped by scale, recycling capability, and proximity to fast-growing heat pump and construction markets rather than by product innovation alone.
Regional Analysis
North America
The North America copper tubes market was valued at approximately USD 3.18 billion in 2024 and is projected to reach USD 3.44 billion by 2030, growing at a CAGR of about 4.0%, supported by HVAC, plumbing, refrigeration, and renewable-energy demand alongside infrastructure upgrades and construction activity.
Europe
Europe represented around 23.2% of the global copper tubes market in 2025, underpinned by stringent environmental regulations and energy-efficient building standards that favor copper's performance in heating and cooling systems.
Asia-Pacific
Asia-Pacific is expected to grow fastest, with industry estimates pointing to a CAGR near 5.7% through 2034, driven by rapid urbanization, industrial expansion, and surging heat pump adoption, particularly in China, which accounts for roughly 40% of global heat pump production and close to 95% of global compressor manufacturing.
Latin America
Latin America shows moderate growth, supported by gradually expanding construction and infrastructure investment across major economies.
Middle East & Africa
The Middle East & Africa region is a smaller but increasingly targeted market, illustrated by Hailiang Group's planned USD 566 million joint-venture copper products plant in Saudi Arabia aimed at serving regional construction and industrial demand.
Emerging Trends in the Copper Tubes Market
1. High-Efficiency, Inner-Grooved Tube for Heat Pumps: Rising heat pump adoption is increasing demand for inner-grooved and thin-wall copper tube engineered to maximize heat-exchanger efficiency.
2. Growth of Recycled and Circular Copper Tube: Producers such as Wieland are investing in copper-scrap recycling and refining lines feeding directly into tube manufacturing, supporting sustainability goals and reducing exposure to raw-material price swings.
3. Continued Industry Consolidation: Large processors are acquiring competitors' tube assets, as seen in Hailiang's purchases from Luvata and KME, concentrating global production capacity among fewer players.
4. Regional Capacity Expansion Closer to Demand Centers: New joint ventures and plant investments, such as Hailiang's Saudi Arabia project and Mueller's Elkhart Products acquisition, reflect a push to localize supply near fast-growing construction and HVAC/R markets.
5. Electrification-Linked Copper Demand: Growth in electric vehicles, renewable energy, and grid infrastructure is reinforcing copper's strategic importance, indirectly supporting investment across copper processors' broader tube, rod, and wire businesses.
Future Outlook (2025–2034)
The global copper tubes market's trajectory toward USD 80.29 billion by 2034 reflects copper's enduring role as the preferred material for plumbing, HVAC/R, and industrial heat-transfer applications, reinforced by the accelerating global shift toward heat pumps and electrified infrastructure. The 6.4% CAGR forecast through 2034 assumes continued construction and renovation activity, sustained heat pump manufacturing growth centered on China, and further consolidation among major producers.
Key investment themes include expansion of recycled and circular copper tube production, continued scale-driven acquisitions among leading processors, and new regional manufacturing capacity aimed at heat pump and construction demand in the Middle East, Asia-Pacific, and North America. Large integrated players including Mueller Industries, Wieland Group, and KME Group are likely to retain strong positions in mature Western markets, while Hailiang Group and Chinese specialists continue to compete aggressively on cost and volume.
Frequently Asked Questions (FAQ)
1. What is the current size of the global copper tubes market?
The global copper tubes market was valued at approximately USD 46.22 billion in 2025 and is projected to reach USD 80.29 billion by 2034, growing at a CAGR of 6.4%.
2. Who are the top companies in the copper tubes market?
Leading companies include Mueller Industries, Wieland Group, Hailiang Group, KME Group, Luvata, Cerro Flow Products, Kobe Steel, Golden Dragon Precise Copper Tube Group, Cambridge-Lee Industries, and MetTube.
3. Which region dominates the copper tubes market?
Asia-Pacific leads global production and consumption, anchored by China's large copper tube manufacturing base and its dominant share of global heat pump and compressor production, while Europe and North America remain significant, mature markets.
4. What is the forecast CAGR for the copper tubes market?
The market is forecast to grow at a CAGR of 6.4% from 2025 to 2034.
5. What are the main growth drivers for this market?
Key drivers include rising heat pump and HVAC/R adoption, ongoing construction and plumbing system renewal, and growing copper demand linked to electrification and renewable-energy infrastructure.
6. What challenges does the copper tubes industry face?
The industry's primary challenges are volatility in copper prices and competition from substitute materials such as PEX and aluminum in some plumbing and HVAC applications.
7. What is the difference between HVAC copper tube and plumbing copper tube?
HVAC and refrigeration copper tube is typically supplied in coils with inner-grooved or smooth-wall designs optimized for heat exchange, while plumbing copper tube is generally supplied in straight lengths sized and tempered for water distribution and drainage systems.
Conclusion
The global copper tubes market sits at the intersection of steady construction-driven demand and the accelerating global transition toward electrified heating and cooling. With a projected size of USD 80.29 billion by 2034 at a 6.4% CAGR, the sector offers durable growth as heat pump adoption, infrastructure renewal, and industrial heat-exchanger demand expand copper tube's addressable market.
Mueller Industries, Wieland Group, and KME Group continue to anchor the market's mature Western regions with vertically integrated operations, while Hailiang Group's scale-driven rise and the continued relevance of specialists like Luvata, Cerro Flow, Golden Dragon, Cambridge-Lee, and MetTube illustrate a market being reshaped by consolidation and regional capacity investment. The producers that pair cost-competitive scale with recycling capability and heat-pump-ready product lines will define market leadership through 2034 and beyond.


